
HOME LOAN REVIEWS · REFINANCING
Same home.
A fresh look at your loan.
Your loan was set up for an earlier chapter. Let’s see how it fits the life you’re living now, and whether a change would be worthwhile.
Phone, video or office appointment. You can start with questions.
Where are you up to?
IF YOU’RE RESEARCHING
Three things worth looking at together.
A review can lead to a better-informed decision, including keeping your current loan.
-
What has changed?
A new income, growing family, different goals or features you no longer use can all prompt a conversation. Start with what you want the loan to do now.
Explore ongoing loan support → -
Your existing lender
Where appropriate, a pricing review with your current lender may be a useful first step. Compare that response before deciding to move.
Rate review or refinance? → -
The whole cost over time
Compare fees, switching costs and the remaining term. A smaller repayment caused by stretching the loan over more years can mean paying more interest overall.
Check whether a change adds up →
WHEN YOU’RE READY TO TAKE A STEP
Bring the details. We’ll work through the comparison.
You can start with a recent statement and your main question. We’ll explain what else is needed.
-
Find your current loan snapshot
Balance, rate, repayment type, remaining term and fees. Note any fixed-rate end date and the features you use. Our worksheet keeps the comparison together.
Get the review worksheet → -
Tell us about your life now
Income, commitments and future plans help frame the review. There is no need to choose a new lender before the conversation.
Prepare for a loan review → -
Check the path before switching
A new lender still needs to assess the application and property. Confirm approval conditions, costs and the transition plan before closing or changing existing facilities.
Understand the lending process →
A USEFUL FIRST STEP · FREE DOWNLOAD
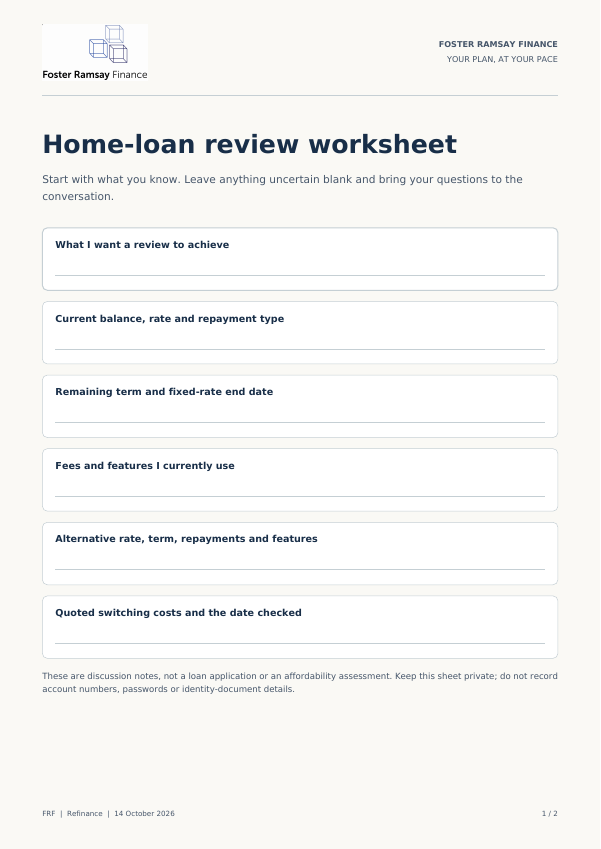
Home-loan review worksheet
Put your current loan and a possible alternative side by side, with space for fees, features and the remaining term. Use it with Chris to check the trade-offs.
- A snapshot of your current loan
- Costs and features to compare
- The questions behind a worthwhile change
2-page PDF · 184 KB · No email required. Print and complete by hand.
Does a review mean I have to refinance?
No. Staying, seeking a pricing change or refinancing can each be a valid outcome. The aim is to understand which option suits your circumstances after the costs and trade-offs are considered.
Can I review a fixed-rate loan?
Yes. Check the fixed-rate end date and ask the lender for any applicable break-cost quote. The amount can change, so use a current figure before deciding.
Will I automatically qualify with another lender?
No. A new lender applies its own credit policy and assessment, including your current income, commitments and the property. An existing loan is not an approval for a replacement.
LET’S TALK IT THROUGH
Know where your loan stands.
Bring your current loan and what you’d like to change. We’ll help you understand the options, including the option to stay.
Ringwood / Melbourne · Geelong · Phone & video
General information only, not an approval or a recommendation for your circumstances. Lending criteria, terms, fees and eligibility apply. Seek appropriate legal, tax and financial advice for your decisions.
Sources and information checked · 14 October 2026
Rules and products can change. Confirm current requirements before acting. Lender examples explain features and are not product recommendations.