
NEXT-HOME BUYERS · MELBOURNE & GEELONG
More room for life.
A plan for the move.
A growing family, a different neighbourhood or a new pace of life. Let’s bring the sale, purchase and repayments into one workable plan.
Phone, video or office appointment. You can start with questions.
Where are you up to?
IF YOU’RE RESEARCHING
Start with the whole changeover.
The next purchase is one part of the move. Put these three things beside the property wish list.
-
What you could use
Equity is your property value less the debt against it. How much you can access also depends on valuation, costs and a lender’s assessment of your circumstances.
Understand usable equity → -
When money is needed
Sale proceeds, the new deposit and settlement may fall on different dates. Include selling costs, temporary accommodation and any overlap in commitments.
Compare the order of the move → -
Life after moving day
Decide what ongoing repayment and savings buffer you want to work towards. A larger home should be considered alongside childcare, work and family plans.
Explore the buying-cost planner →
WHEN YOU’RE READY TO TAKE A STEP
Turn the move into a practical brief.
You don’t need every number confirmed. Bring the estimates and tell us what still needs checking.
-
Gather three numbers
Your current loan payout estimate, the likely net sale proceeds and the full cost of the next purchase. Label estimates clearly; they are not a valuation or lending approval.
Explore property-report information → -
Map the dates and the fallback
Write down the deposit deadline, likely settlements and any gap. Ask what happens if your sale is delayed or the proceeds are lower than expected.
Work through changeover timing → -
Talk before you commit
We can discuss lending options and assessment requirements. Have your conveyancer advise on contract conditions before you make an unconditional commitment.
See what to bring →
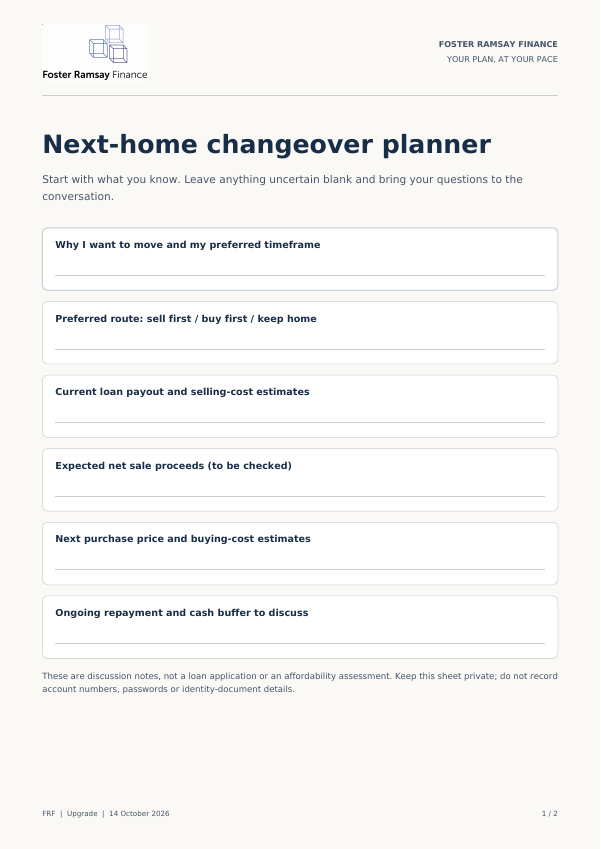
A USEFUL FIRST STEP · FREE DOWNLOAD
Next-home changeover planner
A simple place for the sale proceeds, purchase costs, key dates and a fallback plan. Bring it to the conversation, even if some boxes are still blank.
- Selling, buying or keeping: your preferred route
- The cash and timing gaps to check
- Repayments and life after the move
2-page PDF · 183 KB · No email required. Print and complete by hand.
Can I buy before selling?
It may be possible, but the funding, security, sale timeframe and fallback all need assessment. Bridging finance is not automatically available or suitable. Speak with us before you make a commitment.
Can I use all the equity in my home?
Usually the headline equity figure is different from the amount a lender will let you access. Existing debt, valuation, lending limits and your capacity to repay affect the available options.
Does moving mean I must change lenders?
No. We can explore what your current lender can offer alongside suitable alternatives. Compare the whole cost and structure, including any discharge or fixed-rate break costs.
LET’S TALK IT THROUGH
Make room for the next chapter.
Tell Chris what you want the move to make possible. We’ll work through the lending and timing around that goal.
Ringwood / Melbourne · Geelong · Phone & video
General information only, not an approval or a recommendation for your circumstances. Lending criteria, terms, fees and eligibility apply. Seek appropriate legal, tax and financial advice for your decisions.
Sources and information checked · 14 October 2026
- Moneysmart: buying a house ↗
- CommBank: bridging loan guide (PDF; lender-specific example) ↗
- Moneysmart: buying an investment property ↗
Rules and products can change. Confirm current requirements before acting. Lender examples explain features and are not product recommendations.